How Small Businesses Can Get Paid Faster: Invoicing, Payment Terms, and Late-Payment Follow-Up
For many small businesses, the hardest part of making money is not winning the work. It is getting paid for it. A job can be finished, a product can be delivered, and a client can be perfectly happy, yet the invoice can still sit unpaid for weeks. In the meantime, rent, payroll, supplier bills, and tax obligations do not wait. That gap between earning revenue and holding cash is one of the most common causes of stress for small-business owners, and it is largely preventable.
Getting paid faster is not about being pushy. It is about building a clear, consistent payment system: invoices that leave no room for confusion, terms agreed before work starts, payment options that remove friction, and follow-up that is polite, prompt, and routine. This guide walks through each part of that system, so you can shorten the wait between doing the work and receiving the money.

Why late payment hurts more than it looks
Late payment is not just an annoyance. When a large share of your income arrives late, you may need to delay your own payments, draw on a credit line, or dip into savings meant for growth or emergencies. Over time, that pattern can turn a profitable business into a cash-strapped one, because profit on paper does not pay bills. Only cash does.
The scale of the problem is significant. Intuit QuickBooks reported in its 2026 small-business late-payments research that 59% of US small businesses had invoices overdue by 30 days or more, up from 47% the year before, with an average of about $17,700 owed to businesses waiting to be paid. In the United Kingdom, Sage's SME Performance Pulse for the first quarter of 2026 found that around 49% of SME invoices were overdue, with firms waiting an average of 27 days after issuing an invoice before payment arrived. You do not need to accept those averages as your normal. They are a warning, and a reason to tighten your own process.
The good news is that most late payments are not caused by clients who refuse to pay. They are caused by invoices sent late, terms that were never clearly agreed, invoices missing key details, payment methods that are inconvenient, or simple forgetfulness on the buyer's side. Every one of those causes is within your control.
Start before the work: agree terms in writing
The single most effective step happens before you start work, not after you send an invoice. A short written agreement, even a simple one-page quote or email confirmation, should state what you will deliver, the total price or rate, when payment is due, how the client can pay, and what happens if payment is late. If a client later questions an invoice, you can point to what they already accepted.
At minimum, agree on these points in writing:
- The price and what it covers. State whether taxes, delivery, revisions, or extra hours are included, so the final invoice holds no surprises.
- The payment schedule. Is it full payment on delivery, a deposit plus a balance, monthly billing, or milestone payments? Write it down.
- The due date rule. For example, "payment due within 14 days of the invoice date" is clearer than "payment due soon."
- Accepted payment methods. Bank transfer, card, or an online payment link, whichever you offer.
- Late-payment terms. If you charge a late fee or interest, it must be agreed in advance and comply with the law where you operate. Do not add a fee after the fact and expect it to be welcomed.
If you work with larger clients who insist on their own supplier terms, read those terms before you accept the job. A 60-day or 90-day payment cycle may be standard for that buyer, but it changes your cash-flow planning. Knowing it in advance lets you price, schedule, and negotiate accordingly, rather than discovering it when the invoice is already overdue.
Send the invoice immediately, and make it complete
One of the most common, and most avoidable, reasons for slow payment is a late invoice. If you finish work on Monday and send the invoice the following week, you have already added a week to your wait. Send the invoice the same day the work is delivered or the milestone is reached, while the value is fresh in the client's mind and the person who approves payment still remembers the project.
A complete invoice answers every question the payer might ask, so it does not get sent back or parked in a queue. Include:
- Your business name, address, and contact details, plus the client's name and billing address.
- A unique invoice number and the invoice date, so both sides can track it easily.
- A clear description of the work or products, with quantities, rates, and dates where relevant. Vague lines such as "services" invite questions and delays.
- The total amount due, any taxes, and any deposit already paid, so the balance is obvious at a glance.
- The due date, stated as a calendar date, not only as "Net 30." A date leaves no room for misunderstanding.
- Payment instructions, including bank details or a payment link, placed prominently rather than buried in small print.
- A reference or purchase-order number, if the client uses one. Many corporate accounts cannot process an invoice without it.
If the client needs the invoice sent to a specific person, portal, or email address, use that route from the start. Sending an invoice to a general inbox when accounts payable needs it in a portal is a guaranteed delay.
Choose payment terms that fit your cash flow
"Net 30" means payment is due 30 days after the invoice date. It is common, but it is not a rule you must follow. Shorter terms are perfectly reasonable for many small businesses, especially for smaller projects, services delivered quickly, or first-time clients. Consider these options and choose deliberately, rather than copying whatever you have always used:
- Due on receipt. Best for small, one-off jobs, retail-style sales, and new clients where you want payment right away.
- Net 7 or Net 14. A good middle ground for services and smaller business-to-business work. It signals professionalism without being unusually strict.
- Net 30. Often expected by larger companies and ongoing suppliers, but think carefully before offering it to every client by default.
- Deposit plus balance. For example, 50% upfront and 50% on delivery. This covers your costs, confirms the client's commitment, and halves the amount at risk.
- Milestone payments. For longer projects, split payment across stages: a deposit, a payment at the midpoint, and a final payment on completion. You are never waiting for one large sum at the end.
- Retainers and subscriptions. For recurring work, a monthly retainer paid in advance turns unpredictable income into steady cash flow.
Whatever terms you choose, apply them consistently and state them on every quote and invoice. Inconsistent terms confuse clients and make follow-up harder, because nobody is sure which rule applies to their invoice.
Make paying as easy as possible
Every extra step between receiving your invoice and paying it is a chance for delay. If a client has to print a form, find your bank details, log in to a separate system, or write a cheque, payment can wait until a quieter day that never comes. Reduce that friction.
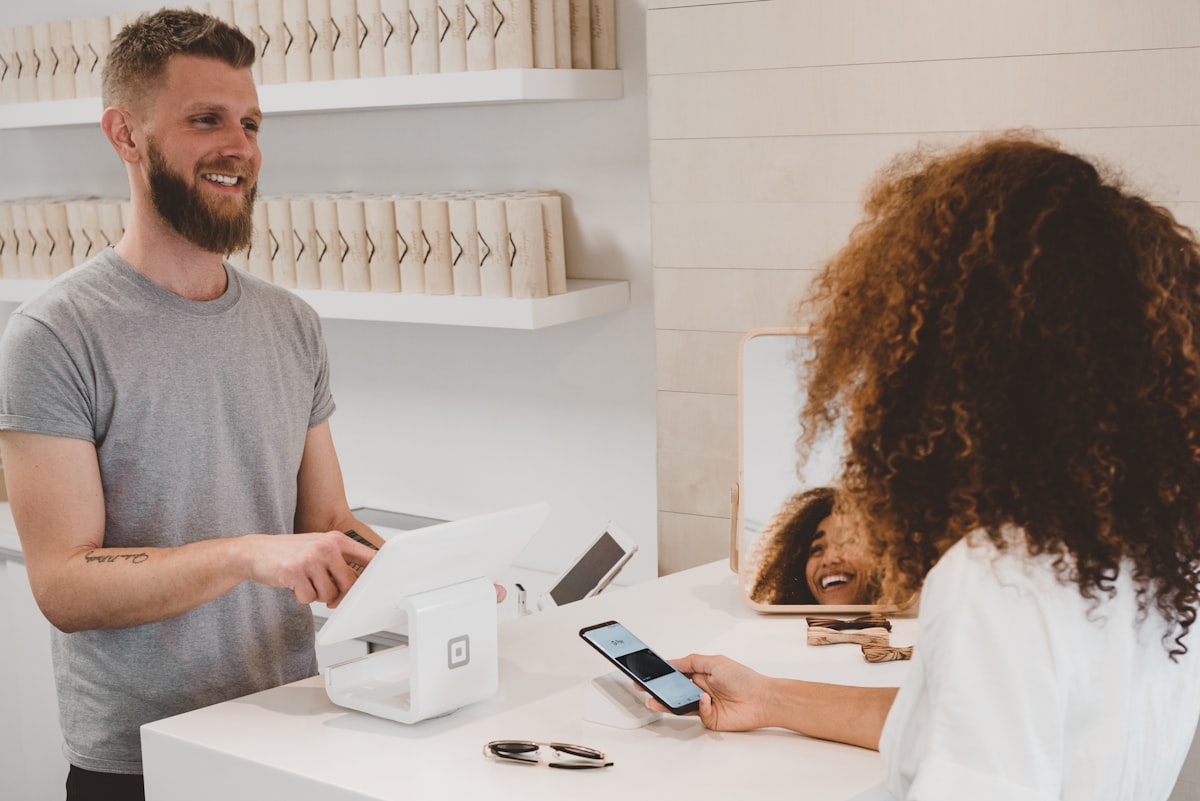
Offer at least one fast digital option, such as an online payment link or card payment, alongside bank transfer. Make the payment link or bank details easy to find on the invoice itself, not only on your website. For recurring clients, ask whether they prefer card billing or direct debit, where available, so future payments happen automatically. And always confirm receipt: a short "payment received, thank you" message builds goodwill and closes the loop.
It is also worth considering early-payment incentives carefully. A small discount for payment within a few days, such as 2% for payment within 10 days, can speed up cash collection for some businesses. But discounts cost you money on every invoice, so use them selectively, for example for large invoices or slow-paying clients, rather than offering them to everyone by default. In many cases, a deposit or shorter terms achieve the same result without giving away margin.
Follow up early, politely, and on a schedule
Many owners delay chasing an overdue invoice because they fear damaging the relationship. In practice, a polite, prompt reminder usually does the opposite: it shows you run a professional business, and it often reveals a simple reason for the delay, such as an invoice sent to the wrong person, a missing purchase-order number, or an approver on leave. Silence, by contrast, teaches clients that your due dates are flexible.
Build a simple follow-up routine and apply it to every invoice, so it feels like a system rather than a personal complaint:
- Three days before the due date: a friendly reminder with the invoice attached again, the amount, and the due date. This catches invoices that were lost or forgotten before they become overdue.
- On the due date, if unpaid: a short, courteous note asking when payment will be made and whether anything is needed from you.
- Seven days overdue: a firmer but still professional message restating the amount, the original due date, and the payment link or bank details, and asking for a specific payment date.
- Fourteen to 21 days overdue: a phone call, not just another email. A conversation often resolves what emails cannot, and it tells you whether there is a genuine dispute or a cash-flow problem on the client's side.
- Thirty days overdue and beyond: a formal notice stating the outstanding balance, any agreed late fee or interest, and the next step if payment is not received, such as pausing further work or passing the account to a collection process.
Keep every reminder short, factual, and free of accusations. State the invoice number, the amount, the due date, and how to pay, and ask one clear question: "Could you please confirm the payment date?" Clients respond better to a specific question than to a general complaint about lateness.
Handle late fees, disputes, and paused work with care
Late fees can encourage prompt payment, but only if they were agreed in advance, are reasonable, and comply with local law. Before adding any fee or interest clause, check the rules that apply in your jurisdiction, or ask an accountant or legal adviser, because the rules differ by country and sometimes by state or type of contract. If a fee applies, state it clearly on the invoice and in reminders, with the amount and the date from which it runs. A surprise fee on an overdue balance often creates a dispute that delays the original payment even further.
If a client disputes an invoice, separate the disputed part from the undisputed part. Ask what specifically is wrong, fix genuine errors quickly, and request payment of any amount both sides agree on while the rest is resolved. A full payment freeze over a small disputed line item helps no one. Document the conversation in writing afterward, so there is a clear record of what was agreed.
For ongoing work, pausing future deliveries until an overdue balance is settled is often more effective than repeated reminders, but use it fairly: warn the client in advance, give a clear deadline, and resume promptly once payment arrives. The goal is to protect your cash flow, not to punish a client who is willing to pay.
Know your numbers: track what you are owed
You cannot improve what you do not measure. At least once a week, review a simple list of unpaid invoices, grouped by how long they have been outstanding: not yet due, 1 to 14 days overdue, 15 to 30 days overdue, and more than 30 days overdue. This is often called an accounts-receivable aging report, and most invoicing or accounting tools generate it automatically.
Two figures are especially useful. The first is your total outstanding balance, so you always know how much cash is waiting to come in. The second is your average collection time, sometimes called days sales outstanding, which is roughly how many days, on average, pass between issuing an invoice and receiving payment. If that number is rising, your terms, invoicing speed, or follow-up need attention, even if sales look healthy. Reviewing these numbers weekly turns payment collection from a crisis into a routine.
Also watch for patterns. If one client is always late, that client may need shorter terms, a deposit, or payment in advance. If invoices for a particular service are always questioned, the descriptions on those invoices may need to be clearer. Patterns point to system fixes, which prevent the same delay from repeating month after month.
Common mistakes that slow payment down
- Sending invoices late. Every day of delay at your end adds a day to the client's payment cycle.
- Using vague descriptions. "Consulting" or "miscellaneous" invites questions. Be specific about what was delivered and when.
- Offering long terms by default. Net 30 or Net 60 may be unnecessary for small, completed jobs.
- Hiding payment details. Bank details or a payment link should be obvious, not hidden in a footer.
- Chasing only when desperate. Follow-up works best as a calm, regular routine, not an emergency.
- Continuing to work for a client who never pays on time. New work for a seriously overdue account increases your exposure. Set a limit and stick to it.
- Mixing personal and business money. When business income lands in a personal account, it is harder to track what is owed, what has arrived, and what is available for business bills. A separate business account makes the whole system clearer.
A 30-day plan to get paid faster
You do not need to rebuild everything at once. A focused month of changes can noticeably shorten your payment cycle. Try this sequence:
- Week 1: Review your current terms and your unpaid invoices. Decide on standard terms for new work, and write a short payment-terms paragraph to add to every quote.
- Week 2: Redesign your invoice template so the due date, total, and payment instructions are unmissable. Commit to sending every invoice on the day work is delivered.
- Week 3: Set up a payment link or card option if you do not have one, and write your three standard reminders: before the due date, on the due date, and seven days overdue.
- Week 4: Start a weekly 15-minute review of outstanding invoices. Contact every overdue account, note the promised payment date, and follow up on that date if payment has not arrived.
After that first month, keep the routine going. The businesses that get paid fastest are rarely the ones with the strictest terms. They are the ones with the clearest invoices, the shortest gap between delivery and billing, and the most consistent follow-up. Clients learn, quickly, that your due dates mean something, and that paying you is easy.
The bottom line
Cash flow is the lifeblood of a small business, and getting paid on time is a skill you can build, not luck you must hope for. Agree terms before work starts, invoice immediately and completely, choose terms that protect your cash flow, make payment effortless, and follow up early and politely on a fixed schedule. Track what you are owed each week, and fix the patterns that keep causing delays.
Start with your next invoice. Send it today, state a clear due date, include an easy way to pay, and set a reminder to follow up before it becomes overdue. Small, consistent habits like these compound over time, just as surely as late payments do, and they leave you with more cash, less stress, and more time to focus on the work itself.
Disclaimer: This article is general educational information about small-business finance, not financial, legal, or tax advice. Payment terms, late fees, and collection rules vary by jurisdiction, so check the rules that apply to your business or consult a qualified professional before changing your contracts or terms.
Post a Comment for "How Small Businesses Can Get Paid Faster: Invoicing, Payment Terms, and Late-Payment Follow-Up"